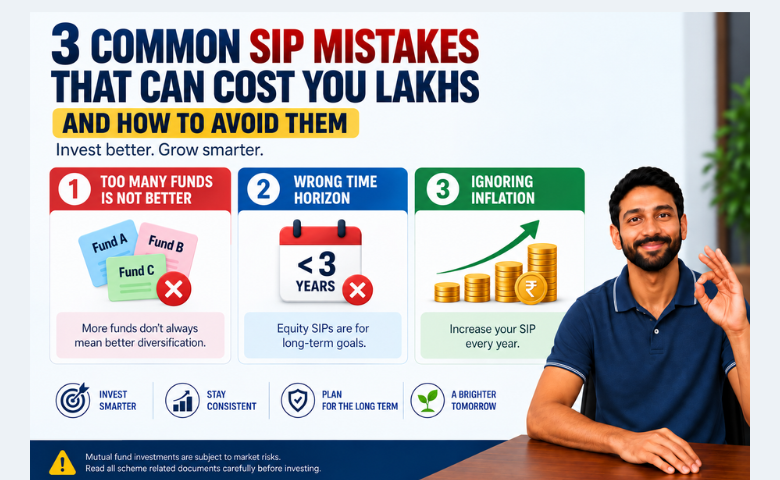
If you're planning to start or already have an SIP, here are three important lessons that can help you invest smarter.
1. More Mutual Funds Don't Always Mean Better Diversification
A common misconception is that owning more mutual funds automatically reduces risk. In reality, over-diversification can work against you.
Many mutual funds hold similar stocks, which means adding more funds often leads to portfolio overlap instead of genuine diversification. It also becomes harder to monitor performance and identify which funds are adding value. As your portfolio grows, you may end up holding low-conviction funds that dilute overall returns.
Instead of chasing every top-performing scheme, you can focus on a limited number of carefully selected funds across different categories such as flexi-cap, mid-cap, and small-cap. A well-structured portfolio is usually more effective than one with too many overlapping investments.
2. Match Your Investment to Your Time Horizon
Equity mutual funds are designed for long-term wealth creation, not short-term financial goals.
If you're investing for a wedding, an international vacation, or a home down payment within the next few years, equity funds may expose you to unnecessary market risk. A sudden market correction could reduce your portfolio value just when you need the money.
As a general rule, investors should have a minimum investment horizon of three to five years for equity mutual funds. For shorter-term goals, debt mutual funds or other low-risk investment options may be more appropriate. Also remember that many equity funds charge an exit load if units are redeemed within a specified period, making early withdrawals even more expensive.
3. Don't Ignore Inflation
One of the biggest mistakes investors make is assuming that keeping the same SIP amount for decades will automatically create enough wealth.
Consider a ₹20,000 monthly SIP invested in a low-cost Nifty Index Fund for 30 years. On paper, it may grow into an impressive corpus. However, after adjusting for inflation, the purchasing power of that amount could be far lower than expected.
Inflation steadily reduces the value of money over time, meaning the lifestyle you imagine today may require significantly more wealth in the future.
A simple solution is to increase your SIP every year. Even a modest annual step-up of around 6%, in line with long-term inflation, can make a substantial difference over time. As your income grows, increasing your investments ensures your future wealth keeps pace with rising living costs.
Another way to improve long-term growth is to avoid relying on a single index fund. A diversified portfolio combining flexi-cap, mid-cap, and small-cap funds can provide broader market exposure and potentially better long-term returns, depending on market conditions and your risk appetite.
Final Thoughts
Successful SIP investing isn't just about investing every month—it's about investing with the right strategy. Avoiding over-diversification, matching investments to your financial goals, and accounting for inflation can significantly improve your long-term outcomes.
Remember, consistency remains the foundation of wealth creation, but combining disciplined investing with thoughtful portfolio construction can help you make the most of your SIP journey.
Note: This is not investment advice, all information shown is for educational purposes only. The schemes and performance data shown are for illustration only and are not to be construed as investment advice or recommendation to buy / sell any mutual fund or other instrument. Mutual fund investments are subject to market risks. Read all scheme related documents carefully before investing. Past performance is not indicative of future returns. Calculations shows are theoretical and not commitments or guarantees of returns. Consult your investment advisor before taking any decisions.